Deutsch
 Français
 Português
 Română
 Türkçe
 中文
 English
 Русский
 Ελληνικά
 Polska
 Italia
 Español


-
Malta EU Presidency Under Spotlight
Malta EU Presidency Under the Spotlight
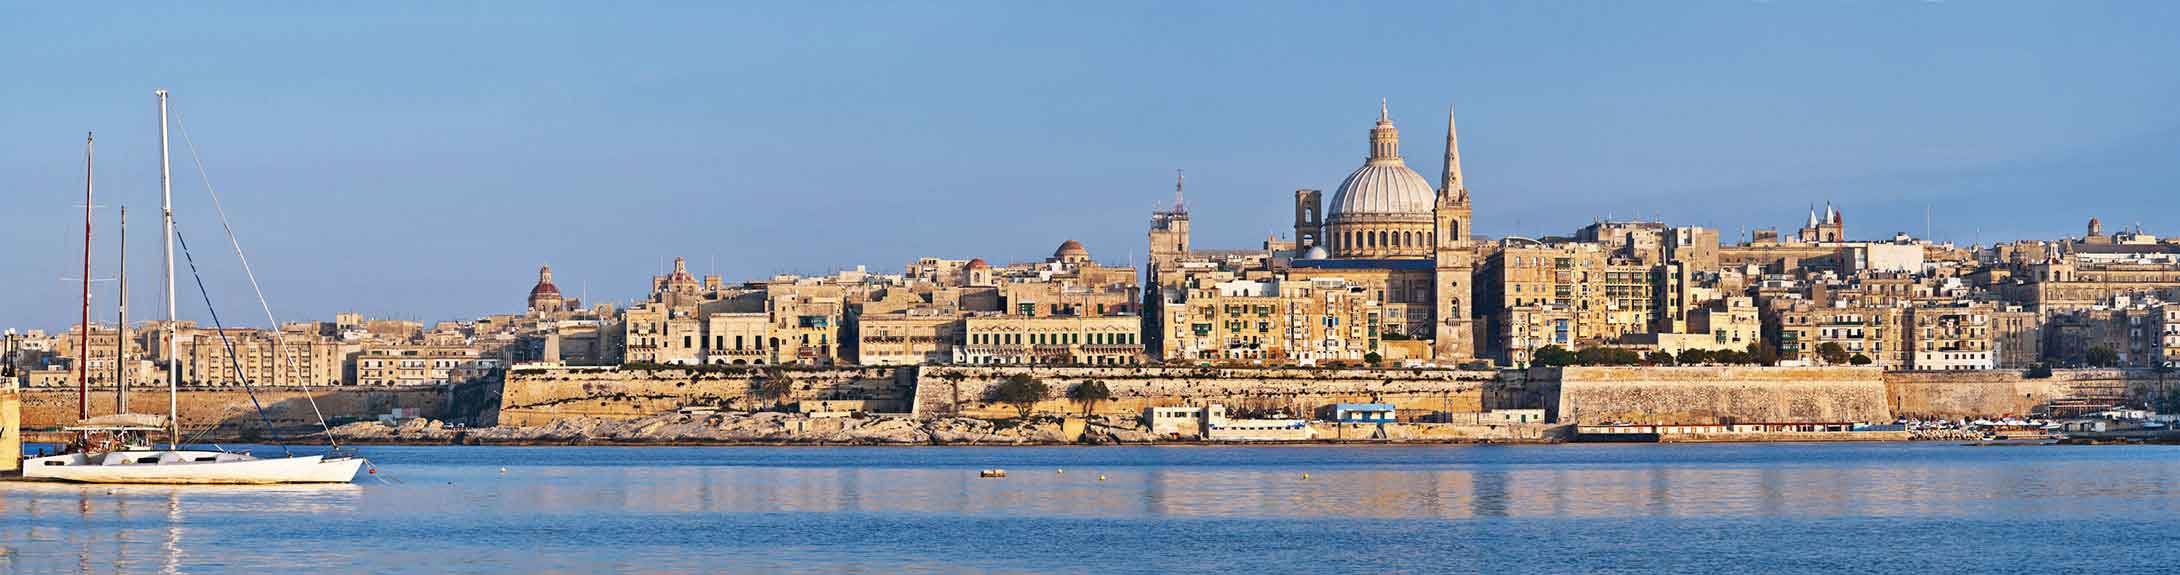
Eyeballs will be on Malta in a few months’ time when it takes over the six-month presidency of the EU Council on 1 January 2017 for the first time. Reports suggest that Malta is well prepared to cope with the unprecedented administrative workload the EU presidency demands.
Over the last 12 years Malta has managed to capitalize on its EU membership, with significant growth in its general economy, including the vibrant financial sector, which is going from strength to strength. In 2015 Malta’s economy registered the second fastest growth within the EU, with the European Commission forecasting Malta’s GDP growth in 2016 and 2017 well above the forecasted figures for the EU as a block.
Malta adopts an EU-compliant regulatory framework, valuable for financial services firms and other organisations to be able to set up their base in Malta and conduct their business within EU and beyond. Complimenting this, other several factors attract such firms, such as the pool of talent and skilled labour, a sound legal system, an advanced financial environment, an adequately capitalised and healthy banking sector, tax incentives to attract foreign professionals, tax credits and favourable corporate and income tax rates.
Consequently, Malta’s unemployment rate dropped to 5.4% in 2015, well below the EU average of 9.4%. The reports for first quarter of 2016 show a further drop to less than 5%.
The increased demand on human capital has pushed the Maltese government to resort to measures to increase the country’s labour force. This includes measures aimed at increasing female participation into the work force. This demand has resulted also in a considerable increase of foreign workers in Malta.
-
Malta Confirms High Investor Confidence Rating
Malta Confirms its High Investor Confidence Rating
During the first Financial Services Survey held in Malta between March and April of 2016, forty-four organizations from across a number of financial industries were asked to rate their performance and business prospects in comparison to their position six months before. Notwithstanding the various challenges being faced by the Financial Services industry, namely increased regulatory control, the EU’s push for increased tax harmonization and the aftermath of the so called Panama Papers, the survey shows 59% of respondents reporting increased business volumes.
Optimism and growth within the Maltese financial services sector remains strong. Within the banking sector, 33% of the respondents report being optimistic about the overall business situation in the sector. Within the insurance sector, 75% of firms reported increased volumes of business with 17% stating that they were more optimistic about the overall business situation in their sector. 55% of asset management firms report increased volumes of business and as much as 60% are expecting business volumes to continue increasing over the coming six months. Increased employment and payroll costs, regulatory compliance and spending on capital expenditure, particularly for IT systems have contributed to increased costs across the board.
The survey also asked respondents to widen their spoke and give their views on the overall situation of Malta’s financial services industry and its future prospects. Respondents retained their positive stance however acknowledged that a number of challenges had to be surpassed in order for the industry to be able to move forward. The general concerns highlighted by the respondents regard the impact of the proposed Base Erosion and Profit Sharing (BEPS) tax rules, the introduction of the Common Reporting Standard, the Brexit referendum and the negative light shed on financial centers across the globe due to the Panama Papers scandal. Respondents also noted the difficulty in opening and maintaining bank accounts locally as a challenging aspect of their business model.
-
Malta Confirms Appeal as Competitive Market Hub
Malta Confirms Appeal as Competitive Labour Market Hub
Malta maintains its position as one of the most stable and one with the lowest social security contributions and employment costs to businesses. On the other hand, the costs of social security and other employment costs have registered substantial increments for employers in other EU countries such as France and the Netherlands. Increased labour costs may act as catalysts for employers to lay off employees, thereby stifling job creation increasing unemployment, particularly youth unemployment.
In addition to the competitive labour market in Malta, the country is a host to and attracts a pool of talent and skilled labour which obviously are necessary to meet the requirements of the dynamic market demands.
There is a strong case for the increase in the social security contributions to sustain the pension system and the ageing population, however Malta has consistently adopted a no- more-costs-policy to employers, whilst at the same time tightening controls and eliminating abuse of the social welfare system. Furthermore, the welfare system is being boosted by the government’s ongoing efforts to create employment, through the implementation of a series of tax credits to employers and incentives to increase the work force, such as the popular free government-run childcare and women returning to work scheme. These implementations together with other tax appealing measures designed to attract foreign business and investment in Malta have managed to reduce unemployment levels to their lowest in the decades.
These sustained policies have over the medium longer term created a stable system which in turn has become a major contributor towards attracting businesses to set up companies and businesses in Malta.
-
Increase in Super Yachts Under the Malta Flag
Marked Increase in Super Yachts Registered Under the Malta Flag
The Malta Chamber of Commerce, via its Yachting Services Business Section has expressed satisfaction at the substantial increase that Malta has consistently registered within the yachting industry over the past years. The increase is not only restricted to registration and the choice of Malta as the flag of choice, but also to ‘value added’ services with a spill-over effect such as berthing, servicing and logistical services.
The Grand Harbour Marina which as of 2015, hosted 159 superyachts, another increase over the figures in 2014, has now further consolidated its position as a well-established player within the Mediterranean basis, with ever-increasing requests for berthing and related services.
As of February 2016, Transport Malta confirmed that the Malta flag had registered an increase of 10.8% over the previous year in the registration of super yachts of over 24 metres in length. The Malta flag is the largest in number worldwide in so far as commercial yachts over 24 metres in length are concerned. Length in excess of 24m also allows investors to consider the long-tested Yacht VAT leasing scheme, whereby crofts in excess of this length can benefit from an effective VAT rate of 5.4% (in lieu of the standard 18% VAT rate) – without distinction between sailing and motor yachts.
The reasons propelling such growth in the super yacht sector under the Malta flag may be summarised as follows:
- Yachts may be registered on behalf of legally constituted corporate bodies or entities irrespective of nationality.
- Low company formation, ship registration and tonnage tax costs.
- Possibility of registration for yachts that are being built or equipped.
- Attractive tax incentives to yachts and super yachts owners encouraging commercial operation.
- No restrictions on the sale or mortgaging of Maltese registered yachts and super yachts.
-
Malta Reiterates its Tax Position
Malta Reiterates its Tax Position at ECOFIN Meeting
May 2016
At the latest Ecofin meeting held in Brussels, Malta together with nine other member states expressed their intention to oppose the approval of a package aimed at stopping tax avoidance, to be discussed during a meeting of EU finance ministers next week.
The proposal’s seek to severely dilute member states’ abilities to make so-called ‘sweetheart tax deals’ with large multinationals, which the EU Commission equates to implicit illegal state aid deals, which can severely distort the common market and effectively give multinationals an unfair competitive advantage allowing them to consolidate and further their market share whilst hindering competition., to the detriment of the consumer and other market players.
Malta’s stance was that it does not engage in any such preferential tax schemes, thereby ensuring a level playing field. It would therefore be draconian and onerous to impose harmonised blanket tax rules under the guise of removal of ‘sweetheart tax deals’. Malta, does not allow any derogation from its tax rules. It employs an attractive tax regime that does not discriminate between one company and another, independently on size, origin of profits, negotiation power etc.
Malta also used the ECOFIN meeting to stress the need to respect primary EU law in the application of anti-abuse legislation. Following the conclusion of the meeting, Professor Scicluna, Malta’s Finance Minister, stated that efforts would continue in seeking and obtaining reassurances on Malta’s tax system.
Malta’s Prime Minister, Joseph Muscat, spoke about the importance of the financial services sector to the local economy, adding that a new approach was necessary to ensure that the local industry remains competitive and relevant in the global context. Speaking at Finance Malta’s ninth annual conference, Prime Minister Muscat concluded by saying that although Malta was in favour of regulations that addressed abusive tax avoidance practices, he urged EU regulators not to move towards a position of over regulation, imposing a one-size-fits-all over member states.
-
Malta Scores Highly on Residency Index
Malta Scores Highly on Residency Index
Malta has been ranked third best place to live worldwide, in a recent survey undertaken by InterNations , narrowly behind Ecuador and Mexico. Just under 15,000 expatriates on a worldwide basis were asked to participate in the survey, and to answer a series of question, ranging from the professional, to healthcare to personal financial and cost of living to establish which jurisdictions were better placed, in providing expatriates with what they perceived as being the optimal basis in an excellent standard of living.
Unsurprisingly, Malta scored highly with British expatriates, based no doubt on the linguistic proficiency of the natives (English is one of the official languages at par with Maltese). Other factors which scored highly was cost of living and friendliness towards foreigners.
Other factors, which scored highly on the list were the pleasant climate (the adage of 330 sunny days holds true), varied and rich heritage, comparatively low cost of living, skilled workforce, quality education, proximity and connections to mainland Europe and superb medical infrastructure. The lack of bureaucracy was also cited by many as one of the underlying reason for choosing Malta as a jurisdiction for the establishment of business, coupled with low labour costs, and multilingual staff.
Malta has a number of bespoke residence schemes, which allow expatriates (EEA and non-EEA) and their respective households to establish their residence in Malta. These schemes consist of a pledge of renting or owning property (the value of which varies on the location of property on the island) as well as a minimum tax endowment. Furthermore, there are a number of bespoke tax incentives for high ranking officers employed in key industries such as remote gaming, insurance, aviation and financial services.
-
Malta MFSA Grants Licence to First Loan Fund
Malta MFSA Grants Licence to First Loan Fund
The Malta Financial Services Authority has granted a licence to the first Maltese-registered loan fund. Loan funds are a recently novel addition, to the Maltese landscape of licensed collective investment schemes. Governed by a bespoke set of rules, loan funds address one of the most frequently asked questions by fund managers – the possibility for funds to grant loans (an activity that was, until the enactment of the rules, the prerogative of banking and credit institutions.
Loan funds, must have at least 70% of their assets, constituted by direct origination of loans by the loan fund or the acquisition of a portfolio of loans or a direct interest in loans. In order to preserve the liquidity of the fund, the remaining 30% must be invested in liquid assets, and the loan funds are precluded from adopting leverage of short selling methods – as a safeguard for diversification, and the curtailing of exposure to the fund investors.
Loan funds may only issue loans to unlisted companies and small and medial sized companies (SMEs). Investment within the fund is limited to professional investors (as defined within MiFID) and the minimum investment, per investor, is set at EUR 100,000.
A loan fund may take various forms as a collective investment scheme, albeit a public limited company with variable share capital (SICAV) tends to be the preferred form. The Loan fund may appoint a custodian, an auditor, a compliance officer and a money laundering reporting officer. The loan fund may be externally managed by a licensed fund manager (duly authorized in terms of the Alternative Fund Managers Directors – AIFMD) or alternatively self-managed, with the management function, being delegated to an investment committee.
Other requirements that are bespoke to loan funds, are the creation of a credit risk policy, liquidity management policy and disclosure, records and reporting.
-
Framework for European Economic Interest
Regulatory Framework for European Economic Interest Group Enacted
One of the cornerstone freedoms of the single European Union is the freedom of establishment. However, this principle is often at odds or at least hindered by the corporate law exigencies of single member states within the European Union. Investors must often wade through a labyrinthine series of different economic and legislative framework, often a hinderance to the small and medium size enterprise, which forms the backbone of the EU economy.
The enactment of a pan-European regulatory framework has been enacted in the form of the European Economic Interest Grouping (EEIG), by means of Council Regulation (EEC) No. 2137/85 (“the Regulations”) which have since been transposed in the Maltese Companies Act.
An EEIG allows the creation of a legal entity, which has a separate legal personality from its founders, and which can operate in any EU Member State. An EEIG is formed by means of a contract of formation and registration at the responsible Authority in the desired member state. The EEIG may be formed either by natural or legal persons or a mixture of both, insofar that the members of the EEIG consist of legal persons whose central administration is in different Member States (the rationale behind the EEIG remains after all the consolidation of a pan-European rather than a purely domestic framework).
Members of the EEIG may, just as they have chosen a designated jurisdiction of choice, may just as swiftly, elect, in the face of changing fiscal circumstances, to move the EEIG elsewhere. This is expedited via a transfer request to the competent authority in which the EEIG has been formed, conditional to the elapse of a two month window.
The enactment of an EEIG framework shall render the proposal of a Maltese registered EEIG ever more attractive, regard being had to its simplicity, low fiscal burden (effective tax leakage of trading companies can be as low as 5%) as well as flexibility. Malta remains well placed to reap full benefits of such EEIG framework by offering a comprehensive and attractive jurisdiction of choice to the savvy investor.
-
Malta Finance Leasing Rules for Aircrafts
Malta Releases Finance Leasing Rules Relating to Aircrafts
In yet another installment aimed at incentivizing the thriving aviation industry (following the VAT guidelines on aircraft leasing and highly qualified person rules), the Maltese authorities have released finance leasing rules relating to aircrafts.
A lease shall be deemed to constitute a finance lease, when it has a number of characteristics, all of which must be satisfied cumulatively, these being:
- The lessor is a finance leasing company (insofar that it is duly licensed financial institution by the requisite authorities);
- The period of the lease is for a period of at least four (4) years or more, and not shorter than the depreciation schedule prescribed by law;
- Notification of the lease contract is given to the Commissioner of Inland Revenue within three (3) months from the lease contract on the prescribed form.
Where a finance lease is terminated prior to the expiration of the currency of the lease agreement, notice thereof must be provided to the Commissioner of Inland Revenue within thirty (30) days of the termination of the group relief provisions.
In determining the income that is chargeable to tax, the following scenarios shall apply:
- The lessor is chargeable to tax on the full amount of the lease payments (albeit provisions may be made to income deductions);
- The lessee shall be entitled to a deduction of the full amount of the lease made by him in respect of the lease asset (inclusive of any deductions allowed by law).
Specifically to aviation, the following rules apply to finance lease:
- The lessor is charged to tax on the annual finance charge (this being the difference between the total lease payments less the capital element, divided by the currency of the lease);
- The lessee may, apart from the finance charge, claim a deduction in respect of repairs, maintenance and insurance;
- If the lessee elects to purchase the aircraft on the termination of the lease, and the lessor does not trade in the purchase and sale of the aircraft, the purchase price shall be considered to be of a capital nature – not taxable to the lessor.
-
MFSA Securitisation Cell Companies Regulations
MFSA Releases Securitisation Cell Companies Regulations
One of the most anticipated legislative enactments has been the Securitisation Cell Companies Regulations, enacted on the 28th November 2015, and welcomed as an important milestone in the securitization and reinsurance industry.
At the outset, a Securitisation Cell Company (SCC) is a body corporation constituted or converted as such, with the function of segregating the cellular assets of the Company. An SCC is a single legal person, yet the cell created by an SCC, does not create, a legal person separate from the SCC. In a way the creation of a cell within an SCC, is not dissimilar to the creation of a cell in a Protected Cell Company (PCC) – also used in the insurance industry.
However, the main thrust for an SCC is that of creating a legal framework seeking to achieve the following:
- Enter into securitization transactions in furtherance and pursuant to the Securitisation Act – Chapter 484 of the Laws of Malta; or
- Assume risks as a special purpose vehicle for the purpose of reinsurance, from a transferring undertaking through the ceding of reinsurance contracts.
There are however, a series of set rules, for SCCs to abide by. At the outset:
- SCC are limited in their scope and contractual abilities by their non-cellular assets. SCCs may not enter into any forms of securitization transaction or risk transfer arrangements beyond their non-cellular assets;
- The Cellular assets of a cell must be held as separate and identifiable from other assets and liabilities of other cells. The cellular assets shall comprise the proceeds of a cell, share capital, attributable reserves etc;
Effectively, this means that the assets of a cell are not available to the creditors of other cells. Creditors have no recourse to the assets of other cells, nor may they enforce their rights vis-à-vis non-cellular assets. The same principle prevails in the case of insolvency. The insolvency attributable to one cell, has no bearing, nor spill-over effect towards the solvency of other cells.
- Since, a cell is incapable of separate legal personality from the SCC, it may only come into existence, through a board resolution of the directors of the SCC.
- Irrespective of whether the cell shall act as a securitization vehicle, or a reinsurance SPV, the prior consent of the MFSA shall be always necessary.
-
Malta Advantageous Tax to Partnerships
Malta Extends Advantageous Tax Regime to Partnerships
The Budget Measures Implementation Act 2015 (published, yet whose enactment is still awaiting Parliamentary approval), shall result in a series of amendments to the Income Tax Act and Income Tax Management Act. Thereby, these measures shall bring a series of reforms to the taxation of Maltese partnerships, effectively resulting in the following:
- Partnerships electing to be treated as companies for tax purposes;
- The requirement for partnerships to carry out a trade or business to be deemed tax transparent; and
- Amendments whereby it shall no longer be necessary for the obligations of the general partner (in partnerships en nom collectif and en commandite) to be unlimitedly liable for all the debts of the partnership.
Whilst, the election for a Maltese registered entity is not a novel feature, the extension of the tax concession to include partnership, shall render the latter more palatable options, in the context of tax planning. Currently, Maltese companies are taxable at 35% corporate tax rate, albeit the immediate shareholders, are, upon a final distribution of dividends, eligible for a series of tax refunds, the default of which is set at 6/7ths of the 35% -thereby bringing the tax leakage to just 5% of taxable income.
This election has been extended in piece-meal fashion to a series of institutes. For example, Maltese private foundations are subject by way of default to the same taxation as Maltese companies. Maltese registered trusts, may, in lieu of evoking tax transparency which would render any income percolating to the trust taxable at the beneficiary level, also elect, conditional to meeting a series of criteria, to also be treated as a company for tax purposes. The extension of such election, which shall be irrevocable once triggered, shall open a new series of opportunities for the use of Maltese partnerships in tax planning.
-
Malta Strong Interest as a Family Office Jurisdiction
Malta Attracting Strong Interest as a Family Office Jurisdiction
Family offices have increasingly become popular, with high net worth individuals, seeking ways and means to safeguard their accumulated wealth, preserve it within the family coffers, and seek tax efficient manners to pass it on to the future generations.
The parameters therefore are to secure an adequate legislative framework which can accommodate the most diversified asset portfolios, yet score very highly with regard to tax optimization and more importantly confidentiality. The ability to transfer ownership in a tax-free environment, as well as having clear and unequivocal rule relating to inheritances and asset transfers are essential.
Malta, has recently enacted a series of legislation that seeks to further complement the existing legal framework. Malta applies no wealth taxes and applies blanket tax exemptions regarding the transfer of assets between non-residents, irrespective of their consanguinity and/or affinity. The use of discrete wealth preservation institutes such as trusts and foundations, is widely used, as well as private collective investment schemes, whose participation is limited to fifteen (15) participants such as family members, friend and acquaintances to the promoters.
The use of trusts as an effective tool within the ambit of family offices has been given new momentum, with the proposal of allowing family trust companies. Currently, the activity of trustees within a Maltese trust (and likewise administrators within a private foundation) is the sole prerogative of licensed entities, approved by the local regulator – the Malta Financial Services Authority. Although, a system of checks and balances may be installed, via the use of protectors with supervisory and veto powers to the trustees, this may result as a hinderance to promoters of family offices, who often prefer hands-on control over assets settled in a trust or endowed in a foundation. New legislation will now allow the creation of family trust companies – whereby the trustee function can now be carried out by Maltese limited liability companies composed of a hybrid of approved resident professionals and family members.
-
Malta VAT Guidelines on Aircraft Leasing
Maltese VAT Department Issues VAT Guidelines on Aircraft Leasing
The Maltese VAT department has recently issued guidelines regarding the VAT treatment of aircraft leasing arrangements. The aforesaid aircraft leasing arrangements are similar in nature to the guidelines issued for the widely known yacht leasing scheme, whereby the applicable rate of VAT were determined on the basis of use and enjoyment of the vessel. In essence, the larger the vessel, the less time the yacht would be deemed to be inside Maltese territorial waters, thereby benefitting, by means of sliding scale, to a progressively reduced VAT rate, of up to 5.4% for yachts in excess of 24 metres in length.
The same principle has been extended to aircrafts. Given the mobility of the crafts, and the inability to determine the actual use of the aircraft within the EU airspace, the Maltese VAT department has issued a series of parameters, whereby when completed shall yield the applicable rate of VAT. The requested parameters for the calculation of such formula, include the following:
- Type of aircraft;
- Take off weight;
- Fuel Capacity;
- Altitude; and
- Cruising Speed
In a similar pattern to the yacht leasing scheme, the lessor would be a Maltese registered company, operating the aircraft as part of its economic activity. Input VAT incurred on the purchase of the yacht may be deducted. Based on this formula, the Maltese Commisioner of VAT would issue a letter of comfort confirming the applicable rate of VAT, during the tenure of the lease
The applicable rate of VAT charged by the lessor to the lessee (which can be a person – physical or corporate established in Malta) would be the one calculated on the basis of the aforesaid formula – which shall be significantly less than the standard applicable rate of 18%. The minimum applicable VAT rate, shall depending on the specifications be of 5.4%.
At the termination of the lease period, the lessee shall be entitled to exercise an option to acquire the aircraft. As the actual possession of the craft would be acquired in Malta – on the last installment, the full VAT rate of 18% would apply. The Maltese VAT Commissioner would issue a VAT Paid certificate, upon evidence being shown that the lease installments have been paid on a monthly basis, during the currency of the VAT period (the maximum length of which may of sixty months).
-
Fitch Reaffirms Malta’s Credit Rating at ‘A’
Fitch reaffirms Malta’s credit rating at ‘A’ – outlook stable
Credit rating Fitch has endorsed the economic policy undertaken by Malta and confirmed its credit rating of ‘A’ with a stable outlook. In undertaking its assessment, Fitch noted that the island was outperforming EU Member States in terms of GDP growth and employment
The few figures point towards a 3.2% growth of GDP throughout 2014. Inflation is on a downward trajectory at 0.6% and unemployment is currently at around 5.8% – one of the lowest rates within the E.U. The public deficit was in line with projections – at 2.7% with a progressive reduction to 2.1% being projected for 2015. Malta would continue outperforming the E.U average throughout the years 2015 and 2016.
The aforesaid figures are testament to the country’s sound economic policies and resilience in the face of the particularly turbulent year that has hallmarked the performance of the E.U. (whereby the GDP figures point towards a contraction of negative 0.4%). The public debt as a percentage of GDP should be reduced progressively to the below 70% mark (one of the economic criterion that must be met by Member States participating in the Eurozone) by 2020.
Other factors worth of mention in the Fitch report were the reduction in electricity tariffs (incentives to businesses) as well as reforms and restructuring within Enemalta – state energy company.
The aforesaid report is a feather in the cap for Malta and further testament that solid economic policies may be maintained in the most dire financial scenarios, to which Malta as a Eurozone member is not immune to. The said report sheds further light to the reasons why the foreign direct investment in Malta has been increasingly progressively over the past few years, and why the number of new companies incorporated in Malta (an important indicator) has been increasing in double-digit figures over the past years.
-
Malta Fiscal Changes in the 2015 Budget
Malta Announces series of fiscal changes in the 2015 Budget
The Minister responsible for Finance has delivered the 2015 Budget Speech, and delivered a series of changes to the individual tax rate and taxation of property transfers. As of 1st January 2015, a final withholding tax systems shall apply to all taxpayers – irrespective of whether they are body corporates or individuals, following a transfer of property. The final withholding tax of 8% shall be levied on the property’s value (down from the previous 12% withholding tax)m subject to the following:
- A final withholding rate of 5% on the property’s value shall apply to transfer of properties effected by individuals who do not habitually deal in property (in other words not speculators) insofar that the subject property is transferred not later than 5% from date of acquisition; and
- A final withholding tax of 10% calculated on the property’s value shall apply to properties acquired prior to 1st January 2004.
In terms of taxation of individuals, the trend of progressive reduction in the personal taxation has been maintained – with the final taxation for individuals earning less than EUR 60,000 annually reaching the set target of 25% (down from 35% from the 2012 rate). Dividend income remains taxable at 35%. With regard to measures targeting employers and businesses, there has been a 25% reduction in utility rates for commercial premises, and a progressive phasing down of the eco-tax on a number of products, with the eco-contribution being subject to a progressive overhaul in the third quarter of 2015. Start-ups, may depending on their size and investment, be subject to a series of tax credits- of up to EUR 250,000 per year. The following measures are aimed at improving the country’s competitiveness whilst seeking to attract foreign direct investment that can further incentivize job creation.
-
Malta Promotes Further Consultation Regarding Family Trusts
Malta promotes further consultation regarding Family Trusts
The Malta Financial Services Authority has promoted a series of consultation papers leading to the enactment of a regulatory framework regulating ‘family trusts’.
Currently, under the Trusts and Trustees Act, the role of a trustee may only be undertaken by licensed entities, approved by the regulator as ‘fit and proper’ and fully compliant with the fiduciary notions inherent in the office of trustee.
The proposed amendments seek to soften the aforesaid stance, by dispensing the need of authorsation vis-à-vis family trusts. Family trusts are defined as trusts whereby a trust is set up by the settlor for the needs, present and future of family member or dependants, who are related to the settlor. The underlying rationale therefore is to allow a softer regime, given the strictly personal and private nature of the trust.
The trustee function would be undertaken by a trustee company consisting of at least three (3) directors. The composition of the board of directors must be of both family members as well as independent individuals. This allows a balance between having family members overseeing the good governance of the trust, with however, the guidance of qualified individuals, fully conversant with the legal intricancies innate with the role of trustees. The latter role must be a qualified lawyer or accountant, approved by the Authority and independent of the settlor, to ensure impartiality in exercising the role. Impartiality is not confined only to consanguinity or affinity but also to professional rapports that the proposed director in the trustee company may have with the settlor.
The private nature of the trust must be satisfied on an ongoing nature. The trustee company cannot hold trustee to the general public nor act as a trustee on a habitual and continuous basis – as this would defeat the purpose for which the trustee is set up.
The use of family trusts will further cement Malta’s reputation as a trust jurisdiction, and allow families to retain a tighter grip on their wealth management and asset protection.
Follow this link to read more about Malta Trusts and Escrow Services.
MALTA COMPANY FORMATION | CALL US NOW: +356 2338 1500 | EMAIL US | CONTACT FORM
Malta is an EU Member State with an Exceptionally Advantageous Tax Regime
Bookmark This Page- Company in Malta
- Articles posted by FBS Malta
News
BLOGS | RELATED LINKS
Malta Company Formation Fees
Malta Forex Company
Malta Citizenship
Contact Us Now
Malta Company Formation Fees
Malta Forex Company
Malta Citizenship
Contact Us Now
CONTACT DETAILS
1st floor
Assikura Building
Old Railway Track
SVR 9017 St.Venera
Malta
T: + (356) 2338 1500
F: + (356) 2338 1111
E: enquiries@fbsmalta.com
1st floor
Assikura Building
Old Railway Track
SVR 9017 St.Venera
Malta
T: + (356) 2338 1500
F: + (356) 2338 1111
E: enquiries@fbsmalta.com